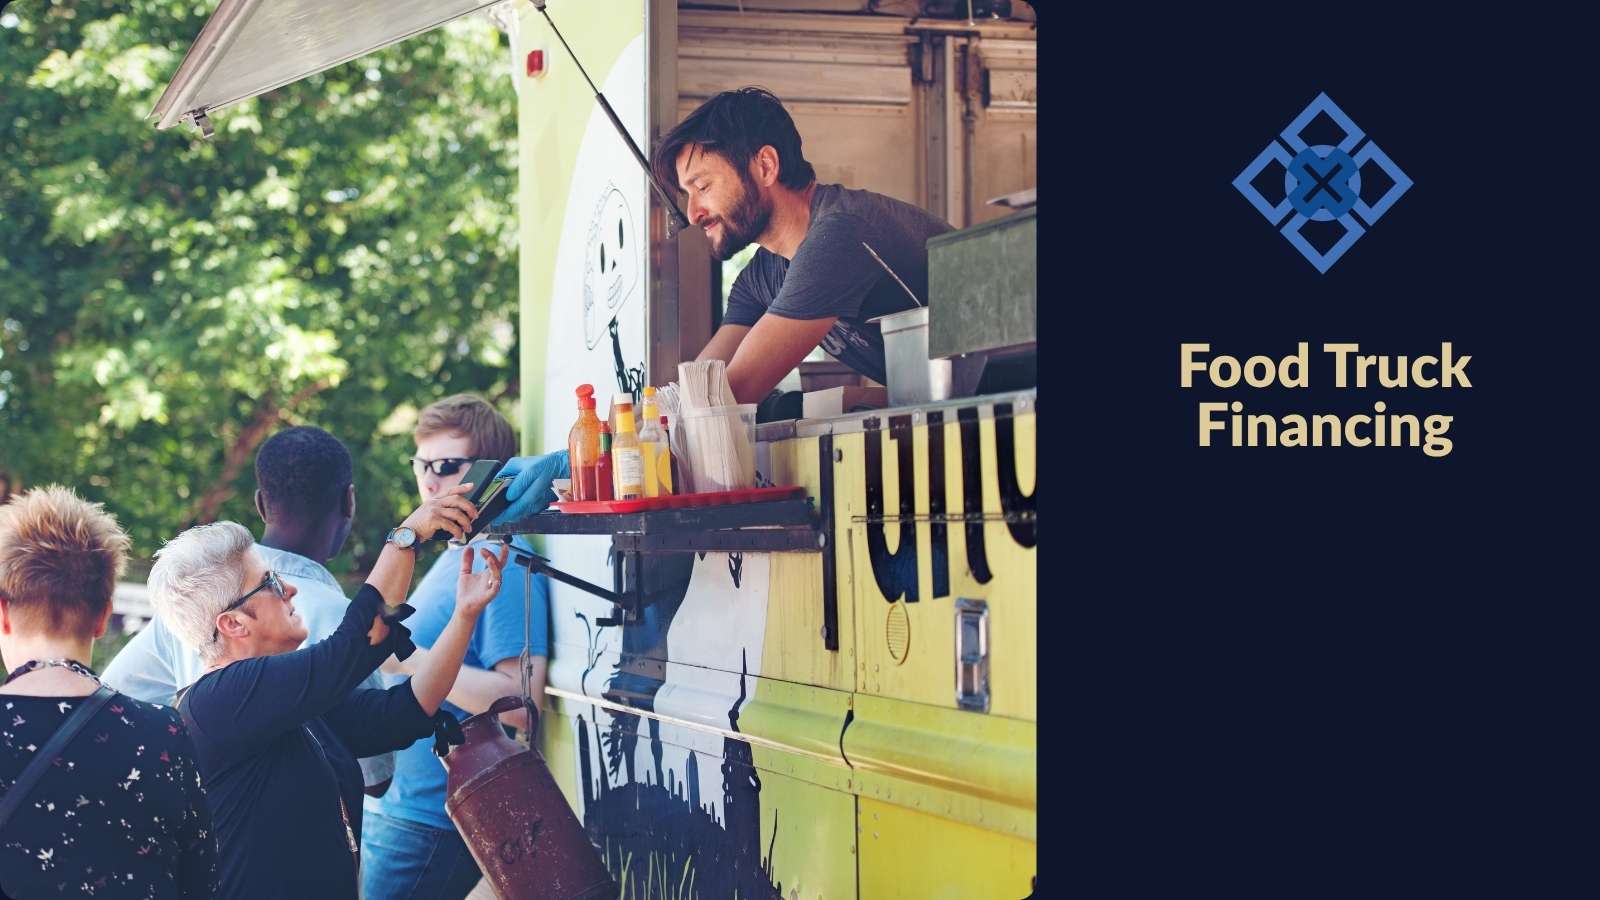
Starting or growing a food truck business takes serious capital — a fully outfitted truck alone runs $50,000 to $150,000 before you factor in permits, equipment, initial inventory, and working capital. Getting the money together often means combining funding sources or waiting years to save up. There's a better way.
Whether you're launching your first food truck or expanding to a second or third, this guide breaks down 5 real financing options — what each is best for, who qualifies, and how to decide which one fits your business stage.
TL;DR: Food truck businesses need between $50,000 and $200,000 to launch and typically need additional working capital within the first year. Your five main financing options are bank loans, SBA loans, merchant cash advances, equipment financing, and alternative funding through a broker. Startups with less than six months in business have fewer options, but established food truck operators qualify for most products. Berkman Financial's funder network can match food truck businesses to multiple options through a single five-minute application.
How much does it cost to start or expand a food truck business?
Before shopping for financing, you need to know what you are financing. Here is a realistic breakdown of food truck startup and expansion costs:
Startup costs (first truck):
| Category | Range |
|---|---|
| Truck or trailer (new) | $75,000 – $150,000 |
| Truck or trailer (used, outfitted) | $30,000 – $75,000 |
| Kitchen equipment | $10,000 – $30,000 |
| Permits and licenses | $2,000 – $10,000 |
| Initial inventory | $1,000 – $3,000 |
| Branding and wrap | $3,000 – $8,000 |
| POS system and tech | $500 – $2,000 |
| Insurance (first year) | $3,000 – $6,000 |
| Working capital (first 3 months) | $5,000 – $15,000 |
Total startup range: $50,000 – $200,000+
Expansion costs (second or third truck): Generally lower per unit because you already have supplier relationships, brand recognition, and operational systems in place. Budget $40,000 to $100,000 for a second truck, depending on whether you buy new or used.
These numbers explain why most food truck operators cannot self-fund entirely. The question is not whether you need financing — it is which type fits your stage.
The 5 main food truck financing options
1. Traditional bank loans
A term loan from a bank gives you a lump sum with fixed monthly payments over a set period, usually at competitive interest rates.
Pros: Lowest cost of capital, long repayment terms (3 to 10 years), builds business credit history.
Cons: Requires strong personal credit (680+), two or more years in business, collateral, and extensive documentation. Approval can take 2 to 8 weeks. Many banks consider food trucks high-risk and decline applications.
Best for: Established food truck operators with strong credit, two or more years of revenue history, and the ability to wait for funding.
2. SBA loans
SBA loans are partially guaranteed by the Small Business Administration, which allows lenders to offer lower rates and longer terms than conventional loans.
Pros: Lowest rates available (typically 6% to 10% APR), terms up to 25 years for real estate and 10 years for equipment and working capital.
Cons: Extremely competitive — approval rates for SBA loans hover around 15% to 25%. Requires excellent credit, detailed business plans, financial projections, and significant documentation. Processing takes 30 to 90 days.
Best for: Well-prepared food truck operators who qualify on credit and documentation and can wait for the SBA timeline.
3. Merchant cash advances
A merchant cash advance gives you a lump sum repaid as a percentage of daily credit card sales. Since food trucks process high volumes of card transactions, MCA repayment aligns naturally with the business model.
Pros: Same-day funding, no collateral, credit scores from 500+ accepted, minimal documentation (bank statements only), flexible repayment tied to sales.
Cons: Higher cost than bank or SBA loans (factor rates typically 1.15 to 1.35). Not ideal for very early-stage businesses without six months of revenue history.
Best for: Operating food truck businesses that need fast working capital — inventory, equipment repairs, marketing, event prep, or seasonal cash flow.
4. Equipment financing
Dedicated financing to purchase or lease the truck itself, along with kitchen equipment, generators, and refrigeration units. The equipment serves as collateral.
Pros: Equipment collateral means better rates than unsecured products, longer terms (2 to 7 years), and often easier approval because the lender can recover the asset.
Cons: Can only be used for equipment purchases, not general working capital. May require a down payment of 10% to 20%.
Best for: Purchasing your first truck, upgrading to a newer truck, or buying expensive kitchen equipment.
5. Alternative business funding through a broker
Working with a business loan broker (also called an ISO) gives you access to multiple funders through a single application. The broker shops your file across their network and brings back competing offers — MCAs, lines of credit, revenue-based funding, and more.
Pros: One application, multiple options. Faster than banks, more options than going direct to any single funder. A good broker explains the tradeoffs and helps you pick.
Cons: Alternative products are typically more expensive than bank financing. The broker is an intermediary (though they are paid by the funder, not you).
Best for: Food truck operators who want to compare options, have been declined by banks, or need funding faster than traditional channels allow.
Food truck financing for startups vs. established businesses
Your financing options depend heavily on where you are in the business lifecycle.
Pre-launch or under 6 months:
Options are limited. Most alternative funders require six months of revenue history. Your best paths are personal savings, SBA microloans (up to $50,000), equipment financing (where the truck is collateral), or friends-and-family funding. Some community development financial institutions (CDFIs) also offer startup-friendly loans.
6 months to 2 years in business:
The full range of alternative funding opens up. You qualify for MCAs, revenue-based funding, and lines of credit through our funder network. Equipment financing is also available for second trucks or major upgrades.
2+ years with strong revenue:
You are in the best position. Bank loans, SBA loans, equipment financing, and all alternative products are available. At this stage, focus on cost — compare bank options against alternative products and choose based on timeline and total cost.
Credit score requirements for food truck financing
| Product | Typical minimum credit score |
|---|---|
| Bank term loan | 680+ |
| SBA loan | 680+ |
| Merchant cash advance | 500+ |
| Equipment financing | 600+ |
| Revenue-based funding | 500+ |
| Business line of credit | 580+ |
If your credit score is below 680, traditional bank and SBA options are effectively off the table. But most food truck businesses can still access merchant cash advances, revenue-based funding, and some equipment financing products. Credit score is one factor — revenue, time in business, and cash flow matter more for alternative products.
How to prepare to apply for food truck financing
Before applying, gather these items to speed up the process and strengthen your application:
- Three to six months of business bank statements — this is the most important document for alternative funders
- A clear use-of-funds plan — even if the funder does not restrict use, knowing why you need the capital helps your advisor match you to the right product
- Equipment quotes — if you are financing a truck or equipment purchase, have a quote or listing price ready
- Current P&L or revenue summary — not required for most alternative products, but helpful for stronger terms
- Permits and licenses — proof that your food truck is operating legally
Red flags to avoid when shopping for food truck funding
Not all funders — and not all brokers — operate with your best interest in mind. Watch for:
- Upfront fees before you see an offer. Legitimate brokers and funders are paid at closing, not before.
- Vague pricing. If you cannot get a clear answer on the total payback amount, factor rate, or daily payment, keep looking.
- "Guaranteed approval" claims. No legitimate funder guarantees approval. If it sounds too good to be true, it is.
- Pressure to sign immediately. A good advisor gives you time to review offers. High-pressure tactics usually mean the deal is better for the funder than for you.
- No competing offers. If a broker only shows you one option, they may be optimizing for their commission, not your best deal.
How Berkman's funder network helps food truck operators
Berkman Financial has been matching small businesses — including hundreds of food service operators — to the right funding since 2015. We have funded over $525 million across 10,000+ businesses nationwide.
When you apply through Berkman, your file goes to our network of 40+ funding partners. You see competing offers side by side, and your named advisor explains the tradeoffs — including when a product is NOT the right fit.
What that looks like for a food truck business:
- Need $30,000 for a used truck? We will show you equipment financing and MCA options side by side.
- Need $10,000 for a festival prep? A same-day MCA might be the fastest path.
- Need $75,000 for a second truck build-out? We can combine equipment financing for the truck with an MCA for the working capital.
- Need to cover a slow winter? A line of credit or revenue-based funding gives you flexible access without paying for capital you do not use.
One application. Five minutes. Multiple options matched to your situation.
See what your food truck business qualifies for
Common questions about food truck financing
Can I get financing to buy my first food truck?
Yes. Equipment financing is the most common path for purchasing your first truck, because the truck itself serves as collateral — which often means better terms. You typically need a credit score of 600+, a down payment of 10% to 20%, and a quote for the vehicle. SBA microloans are another option for startup purchases under $50,000.
What credit score do I need to finance a food truck?
It depends on the product. Bank and SBA loans require 680+. Equipment financing typically requires 600+. Merchant cash advances and revenue-based funding accept scores as low as 500. If your credit is below 600, alternative funding through a broker is likely your most accessible path.
How much does a food truck actually cost to start?
A fully outfitted new food truck typically costs $75,000 to $150,000. A used truck that needs kitchen build-out runs $30,000 to $75,000. Adding permits, initial inventory, insurance, branding, and three months of working capital, total startup costs range from $50,000 to $200,000+.
Should I lease or buy a food truck?
Buying builds equity — you own the asset and can sell it later. Leasing preserves cash and keeps monthly costs lower, but you do not own the truck at the end. If you are confident in the concept and plan to operate for 3+ years, buying usually makes more financial sense. If you are testing a concept, leasing reduces risk.
Can I get a merchant cash advance for my food truck?
Yes — if your food truck has been operating for at least six months and generates $15,000+ in monthly revenue. An MCA provides a lump sum repaid as a percentage of daily card sales. Since food trucks process high volumes of card transactions, the repayment model aligns naturally. Funds can arrive the same business day.
How long does it take to get food truck financing?
It depends on the product. Merchant cash advances and revenue-based funding can fund same-day or within one to two business days. Equipment financing typically takes three to seven business days. Bank loans take two to eight weeks. SBA loans take 30 to 90 days.